
Post Updated on February 5, 2026 by Taylor.
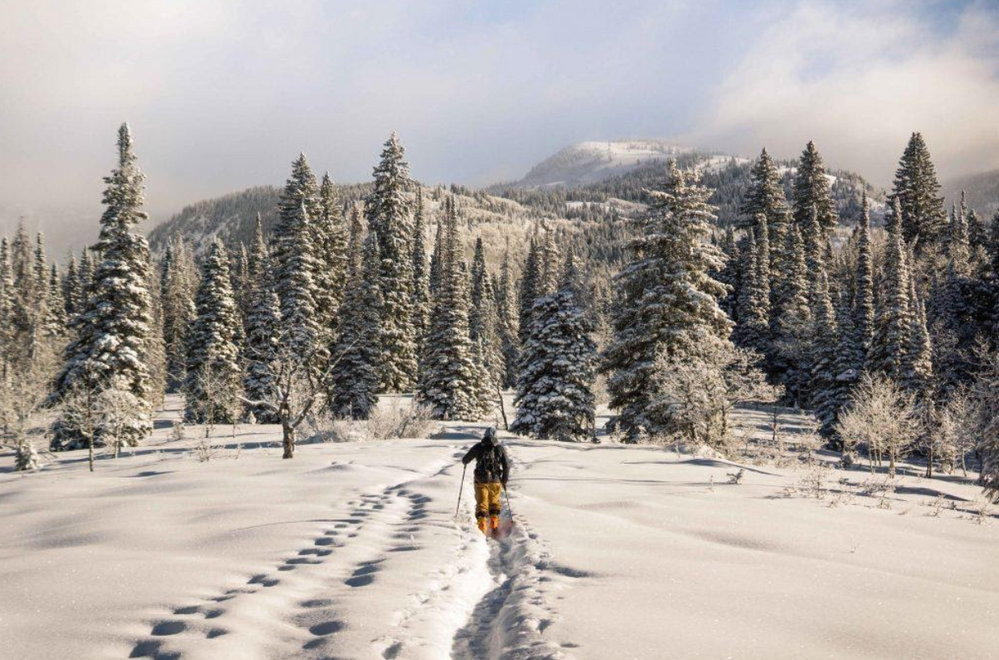
I would best describe backcountry skiing as trekking off the beaten path and out of the safety of a ski resort to “earn your turns.” It’s the ultimate adventure and it greatly tests your physical limits, mental fortitude, and even your leadership skills.
Backcountry skiing has been part of my life for years, long before I ever became a financial planner. And the deeper I get into both worlds, the more clearly I see the parallels. Because whether you’re skinning your way up a ridge line or building meaningful financial freedom for your family, the same principles apply: preparation, risk evaluation, navigation, and teamwork.
As my own financial philosophy has evolved, especially through developing the Mindful Wealth framework, those parallels have become even stronger. Backcountry skiing doesn’t just teach you about strategy. It teaches you about values, intention, and why the journey matters just as much as the destination.
This article is an expansion on my original post from 2021, updated with everything I’ve learned since: from parenting, to refining my practice, to stress-testing portfolios, to uncovering the blind spots that quietly hold people back.
If you’re someone who wants to feel financially confident, aligned, and prepared, these lessons are for you.
1. Preparation: Start With Vision, Not Just Gear
If you head into the backcountry without a plan, you’re not “being spontaneous.” You’re being reckless.
Ask any seasoned skier: preparation starts long before you clip into your bindings. You map the zone. You check the weather. You assess avalanche conditions. You coordinate with your group. You pack the essentials: beacon, shovel, and an avalanche probe.
You prepare because the mountain doesn’t care how confident you feel. It only reacts to the conditions in front of you.
Financial planning is the same way.
Vision Comes First
In my early years as an advisor, I used to jump straight into numbers: projections, cash flow models, investment allocation. And while those tools matter, I’ve learned that the real work begins with your vision.
This became the backbone of my Mindful Wealth framework. A meaningful financial plan begins with three foundational questions:
- Where are you going? (Vision)
- What matters most? (Values)
- Why does this matter to you? (Mission)
Before we build portfolios or tax strategies, we need context. Meaning. Intention.
Preparing for your journey to financial freedom must begin with the end in mind. Identifying goals, creating a plan, and using the right equipment will help build a path to success. I use a goals-based method to help break down the big picture into smaller parts.
Secondly, a good financial plan should have easy-to-follow, pragmatic steps to help you achieve your goals. Your financial plan should include effective saving strategies, diversified investment vehicles, and contingency plans if the plotted course gets slightly derailed. Without a cohesive and practical financial plan, you are left exposed to blind spots that could cause financial catastrophe.
Finally, having the right tools and software is vital to being prepared on your financial journey. Far too often I’ve seen people use back-of-the-envelope math to plan for their financial goals. This results in missing major details, like higher healthcare costs or the impact of inflation over time.
I use state-of-the-art holistic planning techniques to analyze and guide your financial plan.
A well-prepared financial plan can help you handle unforeseen challenges and keep you pushing forward on your path to financial freedom.
2. Risk Is Always There. It’s the Awareness That Matters
One of the humbling truths of the backcountry is that there is always risk. Even on the clearest day, a slope that looks perfect can hide a weak layer beneath the surface.
Skiing in the backcountry increases exposure to the biggest natural risk; a dreaded avalanche. Avalanches kill hundreds of people each year and entering the backcountry without evaluating risks may expose you to grave danger.
An avalanche is created by a breakdown in the snowpack, and the snowpack changes all the time. One of the first steps before skiing is to dig a snow pit. Snow pits allow me to analyze the snowpack to determine the known risks. This includes an analysis of different snow layers, giving you an understanding of how different types of snow interact and the impact of force on a snow slab. After going through this process, the group can determine if the selected slope is worth skiing.
Finance works the exact same way. The surface-level picture can look great: strong income, savings habits, market awareness, good benefits. But when we dig deeper (the tax exposure, the insurance gaps, the investment drift, the cash-flow misalignment) we often find weak layers beneath the snow.
You don’t avoid avalanches by pretending they don’t exist. You avoid them by understanding the terrain.
That’s why I believe so deeply in stress-testing plans. When someone tells me they want to retire at 52, or launch a business, or buy a second home, or shift to part-time work, we model it. We push the plan through different market cycles, inflation environments, tax scenarios, and unexpected events.
Sometimes the results confirm they’re on track. Sometimes they reveal that, at their current pace, they’d run out of money a decade too early. These results offer direction.
Just like in the mountains, risk isn’t something to fear. It’s something to respect. And when you respect it, you can navigate it.
3. Navigation Requires Constant Adjustment
A good backcountry plan gets you started, but it doesn’t guarantee the line you had in mind is safe when you get there. I’ve had countless days when the goal was a specific chute or ridge, only to arrive and realize the conditions were wrong. The slope was reactive. The wind had loaded a cornice. The temperature had shifted.
In those moments, the smartest thing you can do is make a new plan.
Financial planning is remarkably similar. Your life changes constantly: you’ll get new jobs, have more kids, buy new homes, gain new opportunities, confront new fears, create new priorities. And your financial plan has to flex with those changes.
One of my core frameworks at Four Points Wealth is something I call Clarity → Confidence → Execution.
Clarity gives you direction. Confidence keeps you grounded. Execution gets you results.
Most people come to me with one or two of those pieces. Rarely all three. Maybe they know where they want to go, but don’t trust they’re doing enough. Maybe they’re confident in their saving habits, but they don’t have a plan for how it all comes together. Maybe they execute well, but they’re climbing the wrong mountain.
Course correction is a gift. When life shifts, your plan has to shift too. I’ve worked with families who were confident they wanted to retire early, only to discover that staying engaged in meaningful work actually made them happier. I’ve worked with people who dreamed of retiring on a boat or building a vacation home, only to realize their values had changed. I’ve worked with entrepreneurs who thought they’d grow aggressively, then realized they preferred a balanced pace that allowed them to be present with their kids.
These moments allow my clients to reorient to the path that feels best for them. That way, they are always on the right course.
Sticking with a failing plan, on the other hand, can derail your journey to financial freedom indefinitely. Allow yourself the flexibility to alter your course slightly if it ultimately helps you in the long run.
4. You’re Not Meant to Do It Alone
There’s a simple rule in backcountry skiing: you never do it alone. It doesn’t matter how experienced you are or how well you know the terrain. You go with a partner or you don’t go at all.
Harnessing teamwork in the backcountry provides multiple viewpoints to aid in decision making, in the event of an incident, and to have someone to enjoy the amazing adventure with.
When approaching an unfamiliar pitch, it is helpful to have multiple opinions to aid in decision-making. One member may have local knowledge of the area, another may specialize in snowpack analysis, while another may be a very strong skier. Tapping each person’s strengths can lead to better outcomes. Also, there are many unknown hazards and risks that could put you and your group in peril, and your buddies are your lifeline to safety.
In the event of an avalanche where a member is buried, the other group members are charged with searching, digging, and extracting the victim. This reliance requires trust and confidence in each person in the group, so I choose thoughtful and diligent people to share the backcountry skiing experience.
That principle of “not going alone” has shaped how I think about financial planning more than anything else.
Money touches everything in your life. Your family, your work, your anxiety, your dreams, your identity. Trying to shoulder the entire load yourself can be exhausting.
I see this especially with millennial families who are doing so much right. They’re earning well, saving diligently, and investing regularly. But underneath, there’s tension: one spouse feels like they’re overspending, the other feels like they’re not enjoying life enough. One wants to hold cash, the other wants to invest aggressively. One is worried about taxes, the other is focused on retirement.
These aren’t “financial issues” as much as they are alignment issues. And alignment is hard to reach alone.
As a planner and guide, my job isn’t to take over control of someone’s financial life. My job is to widen their field of vision. To show them blind spots they couldn’t see. To bring both partners onto the same page. To stress-test their ideas. To keep them grounded when markets feel chaotic. To remind them what matters when they forget.
Your wealth management team can have a powerful long-term impact on your journey to financial freedom. As a Certified Financial Planner, I provide specialized skills to help identify the best path for you, guide you through challenging financial times, and be your champion when you achieve your financial goals.
I’ve watched couples move from arguing about money to feeling like they’re finally rowing in the same direction. I’ve watched professionals stop questioning every decision and start moving forward with purpose. I’ve watched clients shift from “I hope we’re doing the right things” to “I know we are.”
Your financial advisor is sharing your success. To reach your goals requires grit and having a professional to champion your cause can keep your engine going. I have worked with people who, upon first meeting me, lacked confidence in their financial plans. After following my comprehensive planning process, we found they were closer to their financial dreams than ever imagined.
Backcountry skiing taught me that having the right people by your side isn’t a luxury, but a lifeline. And that’s just as true for your finances as it is for the mountains.
The Ultimate Lesson: Freedom Is Built on the Climb
When I look back on all the time I’ve spent in the backcountry, the most meaningful moments were when I felt fully connected to the mountain, to the people with me, and to myself. In other words, when I am fully present in the experience, I am enjoying it the most.
I’ve come to believe that financial freedom works the same way.
Freedom is the feeling that you’re living a life aligned with what actually matters to you. It’s having clarity, confidence, and a plan that supports the family you’re building. It’s knowing you’re prepared for what’s ahead. It’s trusting your decisions. It feels grounded even when the terrain is unpredictable. It’s understanding how to maximize your wealth in a way that supports who you are, not who you’re trying to keep up with.
That’s why I love this work. Because the parallels are everywhere. The mountain teaches you to slow down, look deeper, adjust your line, and trust your team. And that’s exactly what meaningful financial planning does too.
If you’re reading this and feel like you’re doing a lot on your own, or you’re not sure where to go from here, or you want more intention behind the choices you’re making, I’d love to help you build your map.
You don’t need to skin the mountain alone.
Let’s take the first step together.
DISCLOSURE
Advisory services are offered through CS Planning, Corp., an SEC registered investment adviser
This Content is for informational purposes only, you should not construe any such information or other material as legal, tax, investment, financial, or other advice. Nothing contained on our Site constitutes a solicitation, recommendation, endorsement, or offer by Four Points Wealth Management or any third-party service provider to buy or sell any securities or other financial instruments in this or in any other jurisdiction in which such solicitation or offer would be unlawful under the securities laws of such jurisdiction.
All Content on this site is information of a general nature and does not address the circumstances of any particular individual or entity. Nothing in the Site constitutes professional and/or financial advice, nor does any information on the Site constitute a comprehensive or complete statement of the matters discussed or the law relating thereto. You alone assume the sole responsibility of evaluating the merits and risks associated with the use of any information or other Content on the Site before making any decisions based on such information or other Content. In exchange for using the Site, you agree not to hold Four Points Wealth Management, its affiliates, or any third-party service provider liable for any possible claim for damages arising from any decision you make based on information or other Content made available to you through the Site.
